2.1.1a What an interest rate is
Interest rewards saving and is the cost of borrowing
Interest rate: the price paid to borrow money, or the reward earned for saving money, usually shown as a percentage of the amount over a period such as a year.
- A borrower pays interest on top of repaying the original sum, so borrowing has a cost.
- A saver receives interest added to their money, so saving brings a reward.
- The same interest rate can describe both sides, because a bank pays savers and charges borrowers.
Interest rates are shown as a percentage
- An interest rate is quoted as a percentage of the amount borrowed or saved over a period, usually one year.
- A rate of 4% per year means £4 of interest for every £100 held for one year.
- To read a quoted rate, apply the percentage to the sum of money to find the interest in pounds.
- The pound value of interest rises as the sum of money rises, even when the rate stays the same.
- An interest rate is a percentage, not a fixed pound amount, so the same rate gives different interest on different sums.
- Do not confuse the rate, such as 4%, with the interest earned on a specific sum, such as £4 on every £100.
Risk, term, security and competition create different rates
- Lenders charge more when the risk of not being repaid is higher, since a risky borrower is more likely to default.
- A loan's term, the length of time before it is repaid, also affects the rate, since money is tied up for longer on some loans.
- A secured loan, backed by an asset such as a house, usually carries a lower rate than an unsecured loan, because the lender can seize the asset if the borrower defaults. A mortgage from Nationwide, secured against a house, typically charges a lower rate than an unsecured personal loan from the same bank.
- Competition between banks also matters, since more competition between lenders tends to push rates down, while less competition allows higher rates.
- Savers usually earn a lower rate than borrowers pay, and this gap is how banks make their profit.
The Bank of England base rate guides other rates
- The Bank of England base rate is set by the UK's central bank, and other interest rates tend to move up and down with it.
- As of 30 August 2026, the Bank of England base rate is 3.75%, having been cut from 4.00% to 3.75% on 11 December 2025 and held at every meeting since.
- When the base rate changes, banks tend to adjust the rates they charge borrowers and pay savers in the same direction.
- What does an interest rate mean for a borrower and for a saver?
- Why is an interest rate written as a percentage rather than a pound amount?
- Which factors explain why different loans and savings accounts carry different interest rates?
- What is the Bank of England base rate, and how does it affect other interest rates?
2.1.1b Interest rates and consumer decisions
Higher interest rates encourage households to save more
- When interest rates rise, saving earns a bigger reward, so households are encouraged to save more.
- Money left in a savings account grows faster, making saving more attractive than spending today.
- Some households cut back on current spending so they can put more money aside.
Higher rates discourage borrowing and spending
- When rates rise, borrowing costs more, so households take out fewer loans.
- Big purchases bought on credit, such as cars and furniture, become more expensive to finance.
- Households that borrow less tend to spend less, so consumer spending falls.
- A higher rate helps savers but hurts borrowers, so a rate change is not good news for everyone.
- Households with large debts feel a rate rise as higher repayments, not as a reward.
Higher rates raise mortgage and loan repayments
- Many households have a mortgage, a long-term loan used to buy a home.
- On a variable-rate mortgage, a rise in interest rates raises the monthly repayment.
- Higher repayments leave less disposable income for other spending.
- Changes in the Bank of England base rate feed through to mortgage rates for millions of households.
- Before August 2024, the Bank of England had raised the base rate to a peak of 5.25% to bring down inflation.
- At that peak, households on variable-rate mortgages faced their highest monthly repayments in years.
- The Bank of England has since cut the base rate six times, taking it down to 3.75% by December 2025, where it has been held through 2026.
Lower interest rates do the opposite and encourage spending
- When rates fall, saving earns less, so households are less encouraged to save.
- Borrowing becomes cheaper, so households take out more loans for big purchases.
- Repayments fall on variable-rate mortgages, freeing up income to spend.
- Lower rates therefore tend to raise consumer borrowing and spending across the economy.
- For an explain or analyse question, build a clear chain of reasoning such as higher rate, then dearer borrowing, then less consumer spending.
- Use precise terms like disposable income and variable-rate mortgage rather than vague phrases such as spare money.
- Avoid the trap of treating a rate rise as simply good or bad, since savers gain while borrowers lose.
- If the question gives a figure, use it in your answer, for example applying a stated rate to a stated mortgage amount.
- How does a rise in interest rates affect a household's decision to save?
- Why does a higher cost of borrowing reduce consumer spending?
- What happened to UK mortgage repayments as the Bank of England cut rates between 2024 and 2025?
- How do lower interest rates change household borrowing and spending?
2.1.1c Interest rates, producer decisions and calculations
Higher interest rates raise the cost of business borrowing
- Firms often borrow to fund investment, meaning spending on capital such as machines and buildings.
- When rates rise, the interest charged on a business loan rises, so borrowing costs more.
- A higher cost of borrowing eats into the profit a firm expects from a project.
- The Bank of England base rate guides the rates that banks charge firms, though risk, term, security and competition also affect the rate a firm is offered.
- Before August 2024, the Bank of England base rate had been raised to a peak of 5.25%, making business loans expensive.
- The Bank of England has since cut the base rate six times, to 3.75% by December 2025, where it has been held through 2026.
- Cheaper borrowing since the cuts has made more investment projects worth pursuing for UK firms.
Higher interest rates discourage business investment
- When borrowing is dearer, fewer investment projects are worth doing.
- A project only goes ahead if its expected return is greater than the cost of borrowing.
- Firms may delay or cancel plans to expand when rates are high.
- Some firms save spare cash instead, because saving now earns a higher reward.
- A firm borrows £2,000 at 5 per cent simple interest for a year, so its interest cost is:
- This £100 interest cost is less than the project's expected £150 profit, so the project would still go ahead.
- If the interest rate rose to 10 per cent, the same loan would cost:
- This £200 interest cost is now more than the £150 expected profit, so the project would lose money and be dropped.
Simple interest on savings is calculated step by step
Simple interest: interest calculated only on the original sum, not on any interest already earned.
Principal: the original sum of money that is saved or borrowed, before any interest is added.
- The formula for simple interest is the principal multiplied by the rate and by the number of years:
- A firm saves £5,000 at 3 per cent simple interest for 1 year, worked out step by step:
Step 1: identify the principal, rate and time:
P=£5,000, R=3 per cent, T=1 year P = \pounds5{,}000, \ R = 3\text{ per cent}, \ T = 1\text{ year} P=£5,000, R=3 per cent, T=1 yearStep 2: apply the formula:
Simple interest=£5,000×0.03×1 \text{Simple interest} = \pounds5{,}000 \times 0.03 \times 1 Simple interest=£5,000×0.03×1Step 3: calculate the interest:
Simple interest=£150 \text{Simple interest} = \pounds150 Simple interest=£150Step 4: add the interest to the principal to find the total saved:
£5,000+£150=£5,150 \pounds5{,}000 + \pounds150 = \pounds5{,}150 £5,000+£150=£5,150- After one year, the firm's savings account holds a total of £5,150.
- If the savings rate rose to 5 per cent instead, the same principal and time give:
- This is £100 more than at 3 per cent, so a higher savings rate makes it more attractive for a firm to hold spare cash as savings rather than invest it.
Lower interest rates encourage firms to invest
- When rates fall, business loans become cheaper, so borrowing costs less.
- More investment projects then have an expected return above the cost of borrowing.
- Cheaper borrowing encourages firms to invest in new machines, buildings and jobs.
- Lower rates therefore tend to raise investment across the economy.
- When comparing rates, recalculate the interest at the new rate rather than assuming the change in pounds equals the change in percentage points.
- Apply the rule that a firm invests only if the expected return is greater than the cost of borrowing, and use any figures given in the question.
- Avoid the trap of confusing the interest with the total repayment or the total saved, since the firm repays or receives the principal plus the interest.
- Why does a rise in interest rates raise the cost of business borrowing?
- What rule decides whether a firm goes ahead with an investment project?
- How much simple interest does £5,000 earn at 3% for one year?
- Why does a higher savings rate make a firm more likely to save spare cash instead of investing it?
- What happens to business investment when interest rates fall?
2.1.2a UK government revenue and spending
Government spending runs services, builds assets and supports people
Government spending: money the government uses to run public services, build assets and support people, also called public spending.
- Government spending pays for public services such as healthcare, education, policing and defence, which markets may under-supply on their own.
- It also builds and maintains infrastructure such as roads, railways and hospitals that households and firms rely on.
- A further part supports people who are retired, on low incomes or unable to work.
- Economists sort spending into three types: current spending, capital spending and transfer payments, covered in turn below.
Welfare and the NHS are the largest spending areas
- The list below ranks the largest areas of UK government spending, largest first, using 2024 to 2025 outturn figures, the latest confirmed full-year totals.
- Interest on the national debt appears in this list even though it buys no service directly. It is the price of borrowing in earlier years, so a bigger past deficit means more of today's spending is tied up before it reaches any service.
- Welfare, benefits and other cash transfers: around £313.6 billion, the single largest area, including the state pension and Universal Credit.
- Health: around £190.1 billion, mostly funding the NHS.
- Interest on the national debt: around £104.9 billion, the cost of past government borrowing.
- Education: around £88.8 billion, funding schools, colleges and universities.
- Defence: around £37.5 billion, funding the armed forces and their equipment.
Current spending keeps public services running day to day
Current spending: regular, day-to-day spending on running public services, which repeats every year and is used up quickly.
- Wages and salaries: pay for doctors, nurses, teachers, police officers and soldiers.
- Consumables: medicines, fuel, stationery and cleaning supplies that are used up soon after purchase.
- Maintenance: repairs and upkeep of buildings and equipment that already exist.
- Current spending does not create a new lasting asset, so its benefit is felt mainly within the year it is spent.
Capital spending builds assets that last for years
Capital spending: spending on new, long-lasting assets that will be used for many years.
- New infrastructure: motorways, railway lines, bridges and broadband networks.
- New buildings: hospitals, schools and prisons.
- Major equipment: scanners, military aircraft and large computer systems.
- Capital spending adds to the country's stock of assets and can raise its future productive capacity.
Do not assume all spending in one area is a single type. Building a new hospital is capital spending, but the nurses' wages and medicines inside it are current spending. Judge each item by what the money buys, not by the department.
Transfer payments move money from taxpayers to recipients
Transfer payments: payments to individuals for which the government receives no good or service in return.
- State pension: income for people who have retired.
- Universal Credit and unemployment benefit: support for people out of work or on low incomes.
- Child Benefit and disability benefits: help with the extra costs some families face.
- Transfer payments redistribute income between people rather than paying for output, so they are counted separately from spending on services. The size and mix of spending matters because money used for one purpose cannot be used for another.
Governments raise revenue to pay for everything they do
Government revenue: the money a government raises, mainly through taxation, to fund its spending.
- Governments need revenue to pay for public services such as healthcare, education and defence, to build infrastructure, and to make transfer payments such as pensions and benefits.
- In the 2024 to 2025 fiscal year, the UK government raised £1,148.7 billion in total revenue, equal to 40.8 per cent of national income, while it spent £1,276.2 billion, equal to 45.3 per cent of national income.
- The gap between the two shows how much the government had to borrow that year:
Spending outstripped revenue by around £127.5 billion in 2024 to 2025, the gap the government had to borrow to cover.
Taxation is by far the largest source of revenue
Tax: a compulsory payment to the government, enforced by law, which people and firms cannot choose to opt out of.
- The two largest UK taxes, ranked by revenue raised in 2024 to 2025, were income tax and National Insurance combined, raising around £480 billion, and VAT, raising around £171.2 billion.
- Corporation tax: charged on the profits companies make.
- Council tax and business rates: charged on homes and business premises.
- Fuel duty: charged on petrol and diesel sold at the pump.
- These smaller taxes each raise less than income tax, National Insurance or VAT, though the exact 2024 to 2025 amount for each individually is not published as a single headline figure, so treat these as broad rankings rather than precise totals.
Borrowing covers spending that taxes do not
Borrowing: raising funds now, mainly by selling government bonds to investors, to cover spending that revenue does not.
- When planned spending is greater than the revenue raised from taxes and other income, the government borrows to make up the difference, as it did with the roughly £127.5 billion gap in 2024 to 2025.
- Investors who buy government bonds lend the money in return for interest, so borrowed money has to be repaid later rather than being a permanent source of income.
Borrowing is not free money. It must be repaid with interest, so heavy borrowing today can leave less money for services in the future.
Other income adds smaller amounts on top
- Fees and charges: payments for things like passports, prescriptions and court services.
- Profits and dividends: income from organisations the government owns or has a share in.
- Sales and fines: money from selling assets and from penalties such as speeding fines.
- Taxation remains by far the largest source of government revenue, with borrowing and other income making up the rest.
- Name the three main types of government spending.
- Which single area of UK government spending is the largest, and roughly how much did it cost in 2024 to 2025?
- Is a teacher's salary current or capital spending, and why?
- Give two examples of transfer payments.
- What is the main source of UK government revenue, and roughly how much did it raise in 2024 to 2025?
2.1.2b Direct, indirect and progressive taxation
Taxes are classified in two separate ways
- The first classification asks what a tax is charged on, dividing taxes into direct and indirect.
- The second classification asks how the share of income taken changes as income rises, dividing taxes into progressive, regressive and proportional.
- The two classifications are separate, so any tax can be described using both at the same time, for example as direct and progressive.
Direct taxes are charged on income and profits
Direct tax: a tax charged on income or profits and paid straight to the government by the person or firm being taxed.
- Income tax is charged on the money people earn from work, and National Insurance is charged on earnings too, both deducted straight from wages.
- Corporation tax is charged on the profits that companies make, and is paid directly by the firm.
Indirect taxes are charged on spending
Indirect tax: a tax charged on spending on goods and services, collected by firms and passed to the government, so it can be added to the price the customer pays.
- VAT is charged on most goods and services at the point of sale.
- Fuel duty is charged on the petrol and diesel sold at the pump, on top of VAT.
- The income tax taken from a worker's wages is a direct tax on what they earn.
- The VAT and fuel duty inside the price of a tank of petrol are indirect taxes on what they spend.
Progressive taxes take a bigger share as income rises
Progressive tax: a tax that takes a larger percentage of income as income rises.
- UK income tax is progressive because it is charged in rising bands (2026/27 tax year): no tax on the first £12,570 earned, then 20 per cent up to £50,270, then 40 per cent up to £125,140, then 45 per cent above that.
- Because more of a higher earner's income falls into the higher bands, they pay a bigger percentage of their total income in tax, not just a bigger amount.
Regressive and proportional taxes behave differently
Regressive tax: a tax that takes a smaller percentage of income as income rises, so it takes a bigger share from lower earners.
Proportional tax: a tax that takes the same percentage of income at every income level, so it is a flat rate.
- A flat-rate indirect tax such as VAT is regressive when measured against income, because a poorer household typically spends a larger share of its income than a richer one, so VAT eats up a bigger percentage of a low income than a high one.
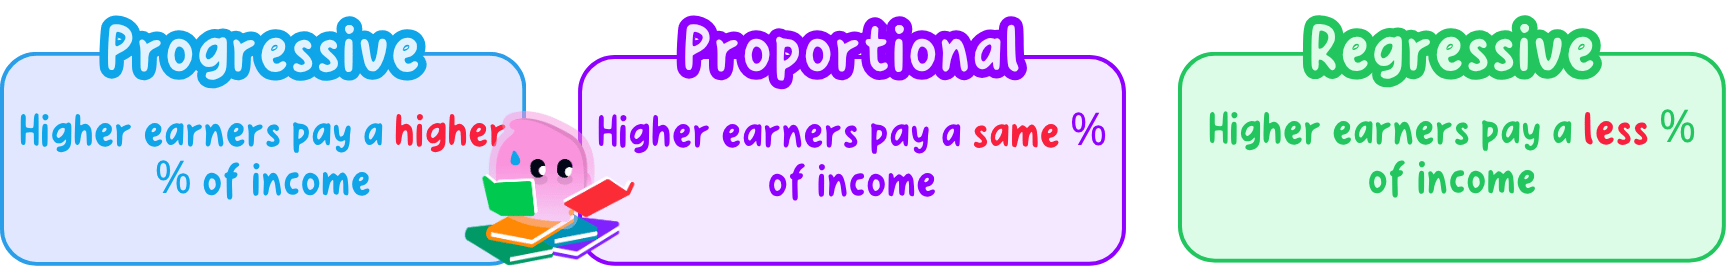
A progressive tax takes a bigger percentage as income rises, not just a bigger amount of money. A flat 20 per cent tax on all income collects more pounds from a richer person but the same percentage from everyone, so it is proportional, not progressive.
A worked example shows why VAT is regressive
- Comparing two households that spend the same amount shows how a flat-rate tax like VAT ends up taking a bigger share of a lower income.
- Suppose two households each spend £6,000 a year, VAT included, on standard-rated goods such as furniture, takeaways and electronics, taxed at the UK standard VAT rate of 20 per cent.
- Household A earns £15,000 a year and household B earns £60,000 a year, but both pay the same £1,000 in VAT.
- VAT takes roughly four times as big a share of household A's income as household B's, even though both paid the same amount, which is what makes a flat-rate indirect tax regressive.
Every tax gets one label from each scale
- Income tax is a direct and progressive tax, since it is charged on earnings and takes a rising percentage as income grows.
- VAT is an indirect and regressive tax, since it is charged on spending and takes a bigger share of a poorer household's income.
- When classifying a tax in an exam, always give both labels to show you understand that the two scales are separate.
- Use the exact terms direct for taxes on income or profits and indirect for taxes on spending, and check the command word, since define wants a precise statement while classify wants the label itself.
- Write the phrase percentage of income when defining progressive, regressive or proportional, so it is clear you mean a share and not a cash amount.
- A common trap is giving only one label when a tax should be placed on both scales, such as direct and progressive together, or claiming VAT takes a bigger amount from the poor when it actually takes a bigger share.
- What is the difference between a direct tax and an indirect tax?
- Define a progressive tax in terms of percentage of income.
- Why is VAT described as regressive, even though everyone pays the same 20 per cent rate?
- Give both classification labels for income tax.
- What is a proportional tax, and how does it differ from a progressive tax?
